
Comparative insight — why this review matters
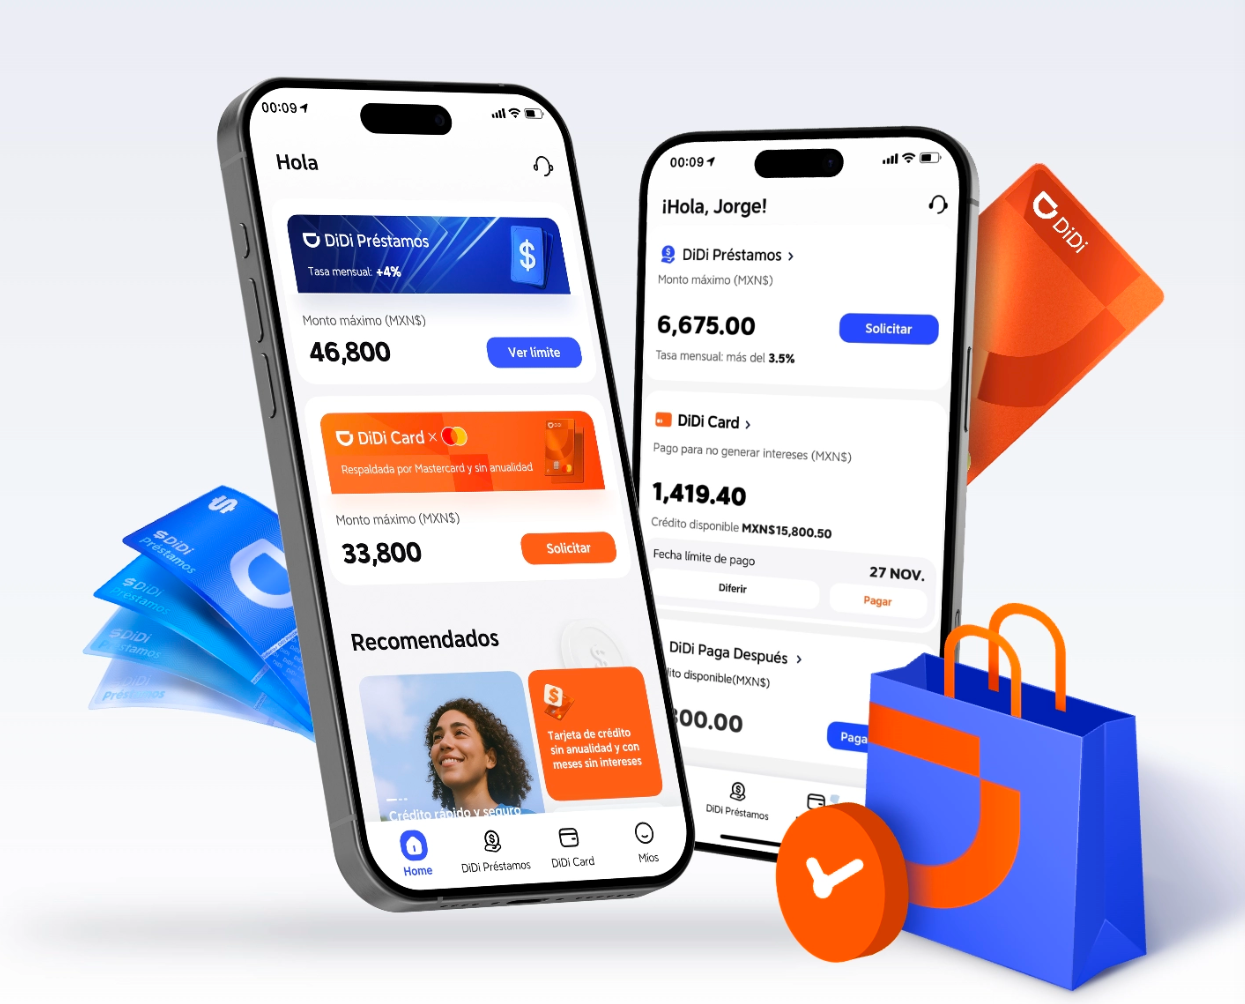
The decision to apply for a DiDi card is a practical financial choice rather than an emotional one. This comparative piece examines fees, rewards, credit mechanics and usability, and it begins with a close look at the DiDi product as presented by didi finanzas in markets such as Mexico City, where ride-hailing and digital payments have grown markedly since the pandemic. I will compare the DiDi offering to a standard digital credit card across measurable categories: cost structure, credit line availability, and day-to-day convenience.
Core features and cost structure
The DiDi card positions itself as a hybrid between a loyalty instrument and a credit facility. Typical features to inspect: cashback on rides, an introductory interest rate, onboarding KYC, and integration with a digital wallet. Compared with mainstream digital credit cards, DiDi’s advantages often appear in targeted cashback for platform spending and reduced transaction fees on in-app purchases. Conversely, standalone digital credit cards may offer broader merchant acceptance, flexible credit lines and tiered rewards. Evaluate the effective interest rate and any hidden transaction fee when you calculate total cost over a billing cycle.
Security and trust — real-world anchor
Trust matters. Consumers in Mexico City and other urban markets have shifted to contactless payment methods since 2020, so reliability and fraud controls are non-negotiable. DiDi emphasizes account verification and transaction monitoring; nevertheless, users should confirm how dispute resolution and chargeback procedures compare with established issuers. For a concise reassurance about reliability, see didi finanzas es confiable which outlines their compliance statements and basic protections. Industry terms to watch here are “fraud monitoring” and “chargeback window”.
User experience and practical value
Practical value depends on your pattern of spending. If most transport and delivery spend happens inside the DiDi ecosystem, the card’s cashback and in-app discounts will compound into meaningful savings. If your expenses are wider—groceries, travel, subscriptions—a broad-acceptance digital credit card typically yields higher overall utility. Application speed, clear statements, and straightforward dispute channels create real usability advantages for either product. Short aside — check mobile app permissions and notification settings; these small items reduce friction in daily use.
Alternatives and common mistakes
Consider three alternatives: a mainstream bank-issued digital credit card, a dedicated neobank card, and a prepaid digital wallet. Common mistakes include applying without checking the effective APR across promotional periods, neglecting foreign transaction fees, and assuming earned cashback offsets late-payment interest. For professionals tracking credit health, monitor your credit score impact when you open new accounts and the utilization ratio on your credit line.
Comparative summary
Direct comparison yields straightforward results: DiDi card is often superior for concentrated platform users due to targeted cashback and lower in-app transaction fees; a general-purpose digital credit card wins on acceptance, flexible credit line options, and sometimes on welcome bonuses. Look at the balance between expected savings from platform rewards versus potential costs from interest rate exposure and annual or transaction fees.
Advisory — three golden rules for choosing
1) Total cost metric: Sum expected annual fees, expected interest if you carry a balance, and average transaction fees to estimate yearly expense. 2) Reward efficiency: Calculate expected cashback as a percentage of your actual spend on the platform, not the advertised rate alone. 3) Credit-fit: Match the offered credit line and reporting practices to your longer-term credit strategy—avoid high utilization spikes that harm your credit score.
These three evaluation metrics will guide a practical decision and help you compare DiDi’s proposition against mainstream digital credit alternatives.
The local convenience and platform alignment make DiDi a sensible choice for frequent users; for broader use-cases, a general digital credit card may suit better. DiDi Finanzas offers a coherent product for its core audience — a solid option, well explained. – practical, local, proven.
