
Start fast — user-first approach
You want a simple, reliable way to split payments without surprises. This guide walks you through activation, configuration, and common pitfalls for DiDi’s pay-later options with clear steps and fast wins. Begin by confirming eligibility and documentation — then visit didi prestamos for account details and application status.
EEAT & real-world anchor
EEAT mode: Practical expertise. These instructions reflect common user flows seen since the COVID-19 pandemic pushed digital credit uptake, especially in urban markets like Mexico City where on-demand services and microcredit became standard. Expect clear, hands-on steps rather than abstract theory.
What the features do — quick primer
DiDi Pay Later creates a short-term credit line tied to your DiDi account for rides and purchases. Buy Now, Pay Later splits a single purchase into installments with a defined repayment schedule and disclosed interest rate or fee. Underwriting is light for many users, but account verification and transaction history still matter.
How to activate DiDi Pay Later — step-by-step
1) Open the DiDi app and go to Wallet or Finance. 2) Locate the “Pay Later” or “Credit” section and tap Activate. 3) Complete identity verification: ID, phone, and a selfie if required. 4) Review the credit line offer, fees, and repayment schedule. 5) Accept the terms and confirm. The app will show your available balance and any soft credit checks performed via API integrations.
Keep your primary payment method updated and enable notifications. Small habit — big difference in avoiding late fees.
Configure Buy Now, Pay Later correctly
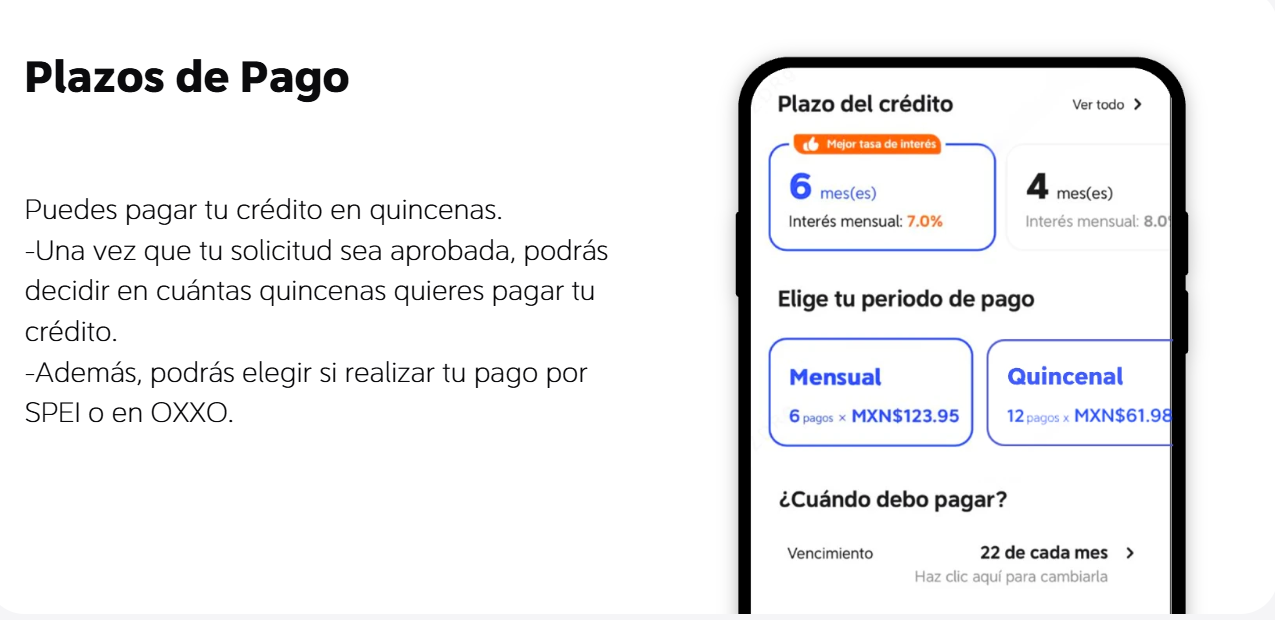
When checking out with a partner merchant or in-app purchase, choose the BNPL option. Read the installment plan: number of payments, due dates, and the exact interest rate or fixed fees. Set an automated repayment method to avoid missed payments; manual payments increase risk. For larger purchases, prefer shorter terms to reduce total interest paid.
Common mistakes and fixes
Ignoring the repayment schedule leads to penalties. Failing to confirm merchant terms can double fees. Don’t assume zero interest — some plans include finance charges. Also, avoid maxing out your credit line; it affects future approvals and can trigger stricter underwriting.
Small practical reminder — clear alerts and a linked debit card solve most problems fast.
Alternatives and when to choose them
If you need flexibility, compare DiDi’s BNPL with a standard credit card, a bank installment loan, or other fintech BNPL services. Credit cards often offer longer grace periods; bank loans give predictable interest rates. Use DiDi Pay Later when convenience and in-app integration save time and the fees are lower than other short-term credit options. Check your didi credito status before applying to understand existing obligations and limits: didi credito integrates account-level info that affects approvals.
Security and best practices
Keep app updates current, use a strong PIN, and monitor transactions daily. Treat BNPL like a short-term loan: track due dates, know the interest rate, and avoid overlapping repayment obligations. If you’re a frequent rider in cities like Mexico City, sync alerts with your daily commute to keep credit use predictable.
Three golden rules for choosing and using BNPL (Advisory)
1) Transparency metric: Always confirm the total cost (principal + fees + interest) before accepting — if it’s unclear, pause. 2) Capacity metric: Compare installment amounts to your monthly cash flow; pick plans with payments under 15% of disposable income. 3) Reliability metric: Favor plans with automatic payment options and clear dispute channels to avoid missed payments and collections.
Apply these rules and you’ll use DiDi’s pay-later tools with fewer surprises — practical, built-in financial flexibility that works with your routine. DiDi Finanzas offers the integrated options that make daily expenses manageable — steady.
