
Start with what matters to you
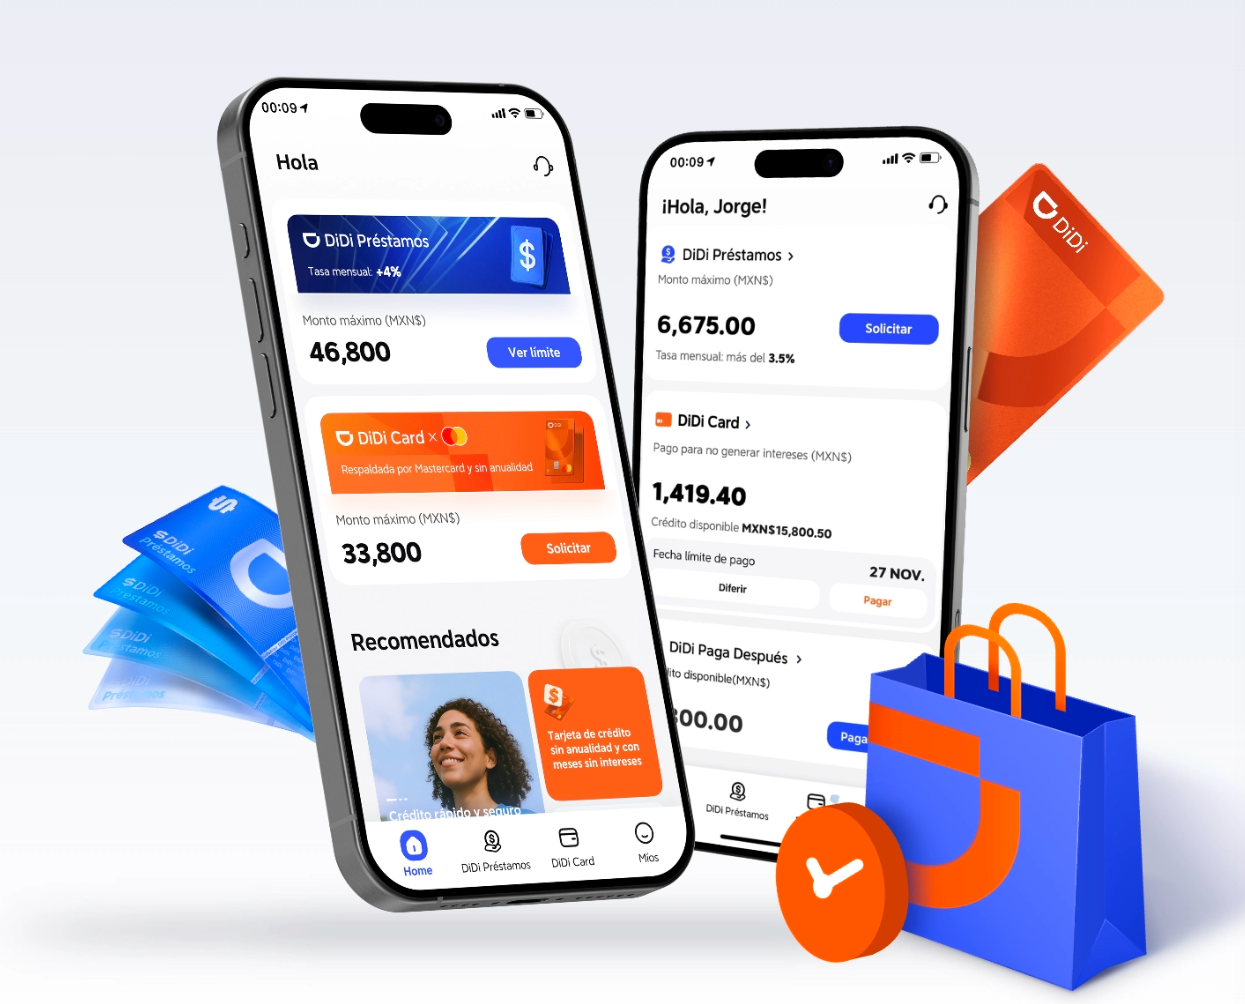
Most folks want the same thing: pay less and worry less. This guide shows a straight path: use your Didi Card together with a virtual credit card to control spend, dodge surprise fees, and squeeze extra value from ride credits or cashback. If you’re checking options, didi finanzas is where the product details and signup live, and they’ll tell you what’s allowed for linking and how rewards apply.
How the combo actually helps
Linking a virtual credit card to your Didi Card gives you two big wins. First, it isolates transport spend — a virtual credit card can have its own billing cycle and limit, so you don’t blow your monthly budget when fares spike. Second, you can route specific promos or cashback to the virtual card for clear tracking. Industry terms here include “virtual credit card”, “billing cycle”, and “transaction fee”, all useful to know when you set limits and watch statements.
Step-by-step — get it running fast
Set it up in three plain steps. Create a virtual credit card through your bank or fintech app. Authorize that card in the Didi app as your payment method. Then set a small top-up or automatic charge cap so you only allow what you budgeted. Keep an eye on two-factor authentication and tokenization settings — they protect the virtual card info without exposing your main account. This takes minutes, not hours, and stops accidental overspend dead in its tracks.
Where this saves money, in practical terms
You’ll see savings in a few places: controlled spend avoids late interest on your primary credit card, targeted promos stack better, and dispute resolution is cleaner if a ride charges wrong — the virtual card narrows the window to contest. Combine that with watching transaction fees, and you cut hidden costs. Real-world anchor: after 2020 fintech adoption rose sharply, especially across Latin America, and many drivers and commuters in cities like Mexico City started using virtual cards to keep daily transport costs predictable.
Common mistakes people make — and how to dodge them
Avoid these three slip-ups: (1) Linking the virtual card without a cap — that defeats the purpose. (2) Forgetting billing cycles — you might get a surprise 30-day charge if cycles misalign. (3) Assuming every promo is combinable. Check terms. Also, keep receipts when disputing charges; it cuts time in support calls. — small habits like this save hours later.
Alternatives and when to pick them
If you don’t want a virtual credit card, consider a prepaid Didi wallet or a debit card with travel protections. Prepaid gives absolute control but loses credit-based protections like short-term dispute rights. Debit is simple but can hurt if fraud occurs. Weigh “fraud protection” versus “budget control” — sometimes you’ll pick one, sometimes both.
Trust and safety — is DiDi Finanzas reliable?
Trust matters when money moves. Look for two-factor authentication, clear refund policies, and transparent API integrations between your card provider and the Didi platform. For more on reliability, see didi finanzas es confiable, where security features and user protections are explained. The practical test: try a small charge first and confirm you can dispute and refund cleanly before migrating your full monthly fare budget.
Wrap-up and three golden rules
Follow these metrics when you decide: 1) Cap control — the virtual card must let you set hard limits. 2) Fee transparency — add expected transaction fees into your monthly transport cost. 3) Dispute process speed — confirm you can reverse an incorrect fare within a short window. Measure those and you’ll know whether the setup actually tightens your wallet or just adds steps. Short take: do the small test, use limits, keep receipts.
Practical moves beat theory; this setup keeps rides predictable, cuts surprises, and makes refunds simpler — and if you want the product details that tie it all together, DiDi Finanzas. –
